For about fifteen years, American banks treated stablecoins like a wildfire on the horizon. Keep an eye on it, talk about it in worried voices, and whatever happens, don’t let it get any closer. Then the GENIUS Act landed and interest in bank stablecoins flipped almost overnight.
Signed on July 18, 2025, the law did something US regulators had put off for a decade. It spelled out how a bank can legally issue a dollar-backed token, and it put a regulator’s name on the process. What came next wasn’t agreement. It was a fork in the road.
Key takeaways
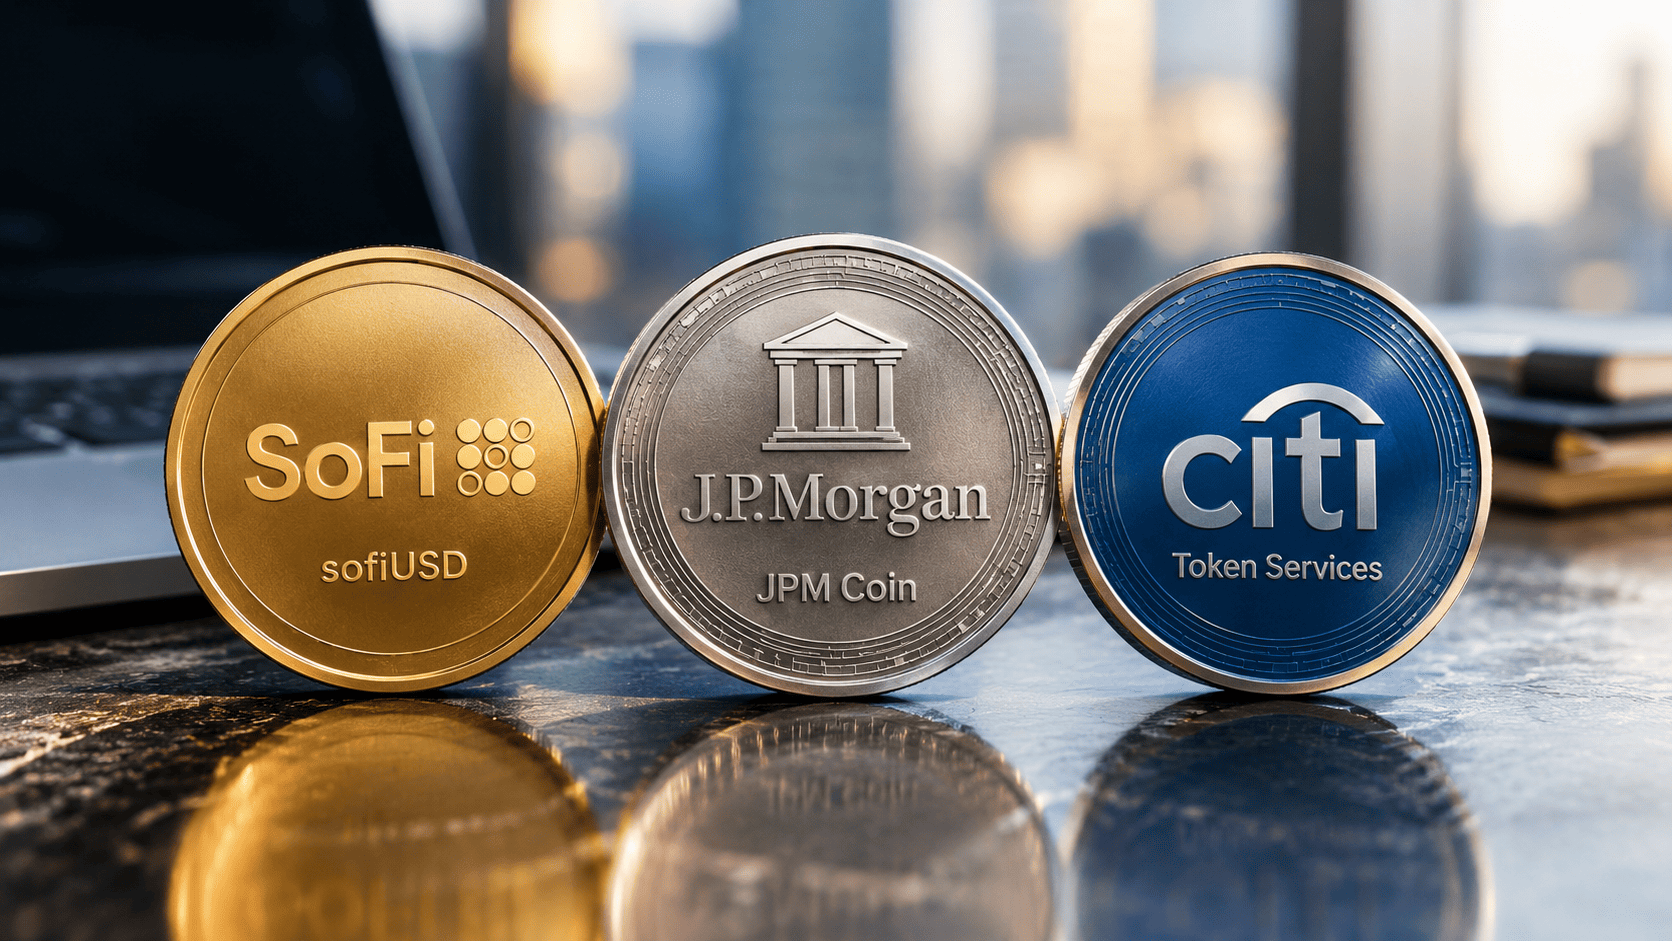
- Three banks have live bank stablecoins today: SoFi (sofiUSD), JPMorgan (JPM Coin) and Citi (Token Services).
- Twenty-one institutions are building a jointly issued stablecoin on public rails. JPMorgan, the biggest US bank, is not one of them.
- Bank of America’s CEO warns that up to $6 trillion in deposits could move to stablecoin rails if tokens are ever allowed to pay yield.
- Four federal agencies are still drafting rules, and the Federal Reserve had issued no proposal of its own at the time of writing.
How the GENIUS Act Turned Bank Caution Into Action
The trigger wasn’t a clever piece of blockchain engineering. It was legislation. Once the GENIUS Act gave banks a legal route to issue stablecoins, the question stopped being “should we?” and became “how, and with whom?”
A second push came earlier this year, when the Federal Deposit Insurance Corporation approved prudential standards for issuers. That effectively started the clock on the current wave of bank filings.
Which Bank Stablecoins Are Already Live in the US?
The fast movers
Three banks got to market first with bank stablecoins you can actually use. SoFi has sofiUSD, JPMorgan runs JPM Coin, and Citi offers Token Services. These are real, shipping products, not press-release promises.
The pilot crowd
A longer list is still in what you could call pilot purgatory: BNY, PNC, U.S. Bank, Wells Fargo, Truist and TD, among others. They’re testing, but they haven’t shipped. Honestly, that part looks like any other technology rollout, with leaders out front and everyone else catching up at their own pace.
The Real Divide: A Shared Network or a Private One
The more interesting split is among the banks that have already decided to act. They’re not building the same thing.
The 21-bank consortium
Twenty-one institutions, including Citi, Goldman Sachs, Bank of America and UBS, are working on a jointly issued stablecoin designed to run on public, interoperable rails. Think of it as agreeing to build one shared road system instead of everyone paving a private driveway. It’s the most ambitious of the bank stablecoins now in development.
JPMorgan’s go-it-alone route
JPMorgan is doing something else. It’s the largest bank in America and it isn’t on the consortium’s list. Through its Kinexys division it has already built proprietary rails, and it appears to have decided that institutional money should stay private, permissioned and under one roof. Its own.
Also Read: Banks Are Racing to Launch Stablecoins as Deposit Risk Grows
The $6 Trillion Fear Behind Both Strategies
Both camps are reacting to the same worry, and Bank of America CEO Brian Moynihan has been unusually blunt about it. He has put a number on the nightmare: as much as $6 trillion of US bank deposits, close to a third of the whole system, moving onto stablecoin rails if regulators ever let those tokens pay yield.
That figure explains a third, quieter project. The Clearing House is building a tokenized-deposit network with JPMorgan, Bank of America, Citi and Wells Fargo all involved. Its goal isn’t to win new stablecoin business. It’s to stop the deposits banks already hold from walking out the door.
So the biggest names are doing two things at once: chasing market share in digital dollars and building walls around the old-fashioned kind. That isn’t indecision. It’s a lot of smart people hedging a bet none of them feel sure about yet.
How Big Is the Market for Bank Stablecoins?
It depends on who you ask. Estimates for regulated stablecoin circulation this year run from roughly $323 billion to more than $500 billion. A gap that wide suggests the exact figure matters less than the direction, and the direction is clearly up.
Regulators Are Still Writing the Rulebook
Here’s the part that should make a corporate treasurer pause, and it’s about timing, not technology. The OCC, the FDIC, Treasury and the NCUA have all been drafting implementing rules in parallel through 2026, and several public comment periods only closed mid-year. The Federal Reserve, notably, had put out no proposal of its own when this was written.
In other words, banks are launching bank stablecoins into a legal structure that is still under construction. That isn’t automatically reckless. American finance has built plenty of infrastructure on rules that finished taking shape afterwards. It’s just worth knowing.
What Corporate Treasurers Should Weigh Before Using Bank Stablecoins
If your company is thinking about running payroll or cross-border payments over one of these rails, remember that the law underneath it isn’t finished. That doesn’t mean stay away. It means read the fine print, and pay attention to which side of the fork your bank picked, because that choice says a lot about how much it trusts a shared financial system versus a proprietary one.
Frequently Asked Questions
1. Are bank stablecoins legal in the US?
Yes. The GENIUS Act gave banks a legal route to issue dollar-backed tokens, though agencies are still drafting the implementing rules, so the bank stablecoins market is working under unfinished regulation.
2. When was the GENIUS Act signed?
The GENIUS Act was signed on July 18, 2025.
3. Which US banks have live stablecoin products?
SoFi (sofiUSD), JPMorgan (JPM Coin) and Citi (Token Services) are the three with live products. Others, including BNY, PNC, U.S. Bank, Wells Fargo, Truist and TD, are still in pilot.
4. Is JPMorgan part of the 21-bank stablecoin consortium?
No. JPMorgan is not on the consortium’s list. It has built its own proprietary rails through Kinexys.
5. What is Brian Moynihan’s $6 trillion warning?
Moynihan, CEO of Bank of America, has said as much as $6 trillion of US bank deposits could migrate to stablecoin rails if regulators allow stablecoins to pay yield.
The Bottom Line
A year into the GENIUS Act era, nobody actually knows which bet on bank stablecoins wins. Not the consortium, not JPMorgan, not the regulators working in four separate rooms. What we can know today is which side of the fork each major bank chose. Over the next eighteen months, that may be a better number to watch than any settlement-speed statistic.
Explore more expert insights, leadership stories, and business strategies at GlobeVox Leaders